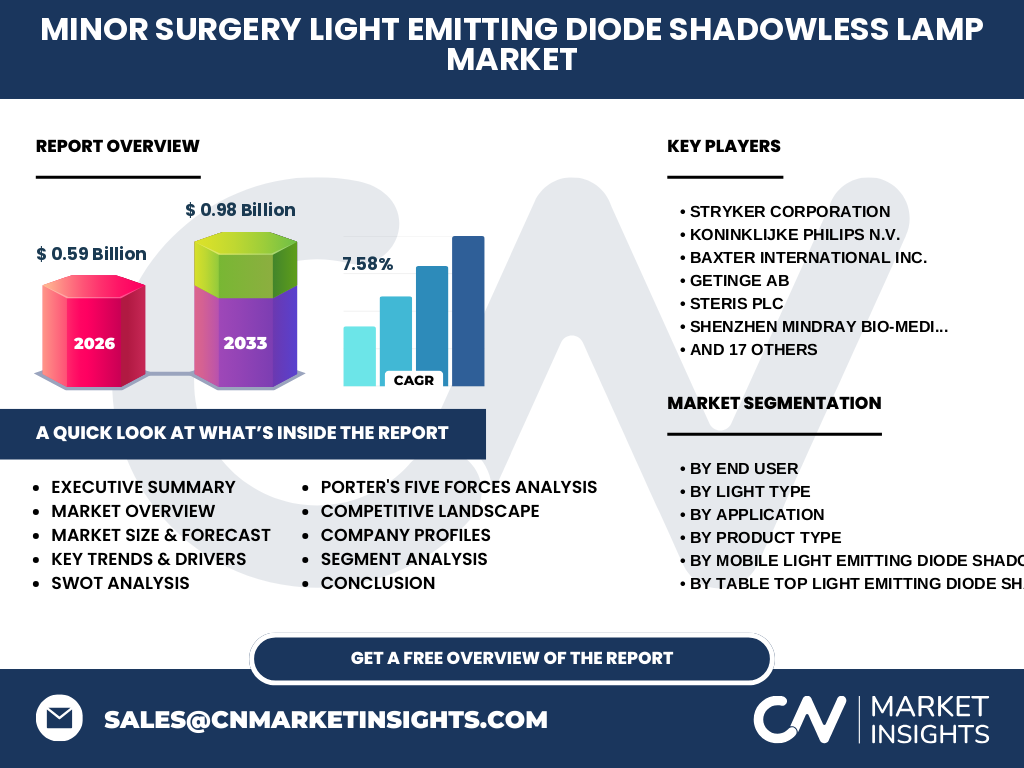
Market overview of the Minor Surgery Light Emitting Diode (LED) Shadowless Lamp Market
Our analysis indicates that the Minor Surgery Light Emitting Diode (LED) Shadowless Lamp Market represents a critical segment within surgical illumination, valued at $0.59 Billion in 2026. This sector encompasses advanced lighting systems engineered for precision outpatient procedures, minimizing cavity shadows through multi-source optical arrays. These specialized fixtures are vital for maintaining optimal color rendering index (CRI) and low thermal emission across clinical environments.
What core factors drive and restrain the Minor Surgery Light Emitting Diode (LED) Shadowless Lamp Market?
The market is propelled by rising ambulatory surgical volumes and stringent FDA and CE compliance standards demanding superior shadow management. However, growth is restrained by high capital expenditure hurdles for premium Adjustable White Light Emitting Diode units and supply chain bottlenecks affecting rare-earth semiconductor components. Regulatory scrutiny by notified bodies heavily dictates technical specifications for domestic commercialization.
Structural Growth Drivers and Emerging Trends
Industry trends highlight a definitive pivot toward Adjustable White Light Emitting Diode configurations offering dynamic color temperature controls for varied tissue visualization. Technological convergence with touchless gesture controls and integrated high-definition cameras is redefining procedural workflows. Manufacturers like Getinge AB and STERIS plc are leading this shift by embedding IoT-enabled diagnostic telemetry directly into surgical light heads.
How did the COVID-19 pandemic impact the Minor Surgery Light Emitting Diode (LED) Shadowless Lamp Market?
The pandemic initially caused severe disruptions in raw material procurement from primary hubs in East Asia, coupled with elective surgery suspensions that stalled hospital capital budgets. Recovery has since accelerated past pre-pandemic baselines, driven by post-COVID investments in decentralized healthcare infrastructure. Facilities rushed to procure Mobile Light Emitting Diode Shadowless Lamps to support rapid expansion of temporary triage and ambulatory surgical setups.
Competitive Benchmarking and Market Concentration
The competitive landscape is moderately consolidated, featuring tier-one medical technology conglomerates competing alongside specialized regional lighting innovators. Key market participants such as Stryker Corporation, Koninklijke Philips N.V., and Shenzhen Mindray Bio-Medical Electronics Co. Ltd. utilize aggressive distribution agreements and OEM partnerships. Their strategic positioning focuses on modular ceiling and wall-mounted architectures to secure long-term hospital group purchasing organization (GPO) contracts.
Executive Summary of the Minor Surgery Light Emitting Diode (LED) Shadowless Lamp Market Analysis
Our comprehensive assessment reveals robust expansion for the Minor Surgery Light Emitting Diode (LED) Shadowless Lamp Market, anchored by a projected market value of $0.98 Billion by 2033. Operating at a solid CAGR of 7.58% from 2027 to 2033, the sector offers high-yield opportunities for stakeholders investing in energy-efficient, thermally optimized, and ergonomically flexible illumination technologies across diversified clinical end-user segments.
Market Forecast and Valuation Trajectory from 2027 to 2033
Based on our econometric modeling, the market valuation will scale systematically from its $0.59 Billion baseline in 2026 to reach $0.98 Billion by the conclusion of 2033. This consistent 7.58% CAGR is underwritten by escalating outpatient surgical procedures and sustained institutional expenditures on healthcare facility modernizations, particularly across North American and Asia-Pacific healthcare networks.
Segmentation Analysis across End-Users, Light Types, Applications, and Product Configurations
Market segmentation spans multiple categories designed for distinct clinical workflows. By end-user, coverage includes Hospitals, Ambulatory Surgical Centers, Medical Colleges And Training Institutions, and Clinics. Light types feature Cool White, Neutral White, Warm White, and Adjustable White variations. Applications comprise Orthopedic, General, Gynecological, Pediatric, and Ophthalmic surgery. Product types range across Ceiling Mounted, Wall Mounted, Mobile, and Table Top LED shadowless lamps.
Regional Market Analysis and Geographic Performance Distribution
Geographic performance exhibits distinct regional variances driven by healthcare reimbursement policies and infrastructure investments. North America leads global revenue generation due to high adoption rates of advanced ambulatory surgical centers. Meanwhile, the Asia-Pacific territory is capturing rapid market share, propelled by expanding healthcare access in metropolitan clusters and localized manufacturing capabilities by companies like Heal Force Bio-Meditech Holdings Limited.
In-Depth Regional Review of Regulatory and Logistical Frameworks
Regional execution requires navigating complex regulatory frameworks, such as FDA clearances in the United States and stringent MDR mandates across European Union markets. Logistical strategies depend heavily on maritime shipping through major commercial ports like Rotterdam and Shanghai for heavy Ceiling Mounted Light Emitting Diode Shadowless Lamps. Localized warehousing mitigates customs clearance delays for sensitive optical assemblies and battery-operated mobile units.
Strategic Positioning of Leading Company Profiles
Industry leaders maintain competitive moats through continuous product innovation and robust global distribution networks. Entities like Baxter International Inc., Drägerwerk AG & Co. KGaA, KARL STORZ SE & Co. KG, and KLS Martin Group focus heavily on ergonomic suspension arms and shadow-reduction algorithms. Meanwhile, specialized players such as Skytron LLC and Amico Corporation target mid-tier ambulatory centers with cost-effective, high-luminance solutions.
Porter's Five Forces Analysis of the Competitive Landscape
Our analysis indicates moderate-to-high competitive rivalry driven by established players offering feature-rich modular lighting arrays. Buyer power remains significant due to consolidated hospital purchasing groups demanding bulk discounts. The threat of new entrants is constrained by high regulatory compliance hurdles, stringent ISO quality standards, and proprietary optical engineering patents held by incumbents like Herbert Waldmann GmbH & Co. KG and Simeon Medical GmbH & Co. KG.
SWOT Analysis of the Minor Surgery Light Emitting Diode (LED) Shadowless Lamp Market
Key strengths lie in superior energy efficiency and exceptionally long operating lifespans of LED diodes compared to legacy halogen systems. Weaknesses involve high initial setup costs for complex multi-dome setups. Opportunities thrive in emerging market healthcare infrastructure upgrades, while threats stem from aggressive price competition by unverified third-party component manufacturers.
Value Chain Analysis from Raw Materials to End-User Delivery
The value chain initiates with upstream extraction of raw semiconductor materials, rare-earth phosphors, and high-grade aluminum for thermal heat sinks. Midstream manufacturing involves precision optical lens molding, circuit board assembly, and rigorous photobiological safety testing. Downstream distribution flows through specialized medical equipment distributors directly to end-users like ALVO Medical Sp. z o.o., Brandon Medical Co. Ltd., and Mediland Enterprise Corporation.
Investment Insights and High-Potential Strategic Areas
Investors should direct capital toward companies engineering Battery Operated Mobile Light Emitting Diode Shadowless Lamps and IoT-integrated touchless control interfaces. Strategic acquisitions of niche optical engineering firms offer high-potential entry points. Market entrants must prioritize compliance-ready supply chains to capture high-margin opportunities within expanding ambulatory surgical centers globally.
Conclusion and Strategic Takeaways for Industry Stakeholders
The Minor Surgery Light Emitting Diode (LED) Shadowless Lamp Market presents a compelling growth narrative, transitioning from $0.59 Billion in 2026 to $0.98 Billion by 2033 at a 7.58% CAGR. Success requires balancing technological innovation in color-adjustable lighting with rigorous regulatory navigation across global healthcare jurisdictions.
Research Methodology and Baseline Estimation Triangulation
Our research methodology employs a rigorous triangulation approach combining primary stakeholder interviews with C-level executives, R&D directors, and procurement heads across major hospitals. Secondary data extraction leverages customs trade registries, corporate financial filings from entities like Inspital Medical Technology GmbH, Avante Health Solutions DRE Medical, Nuvo Surgical Lighting LLC, Eschmann, and ACEM Medical, alongside macroeconomic healthcare expenditure databases.
Scope of the Report, Coverage Parameters, and Analytical Limitations
This report evaluates the global market across specified product types, light configurations, end-user verticals, and regional territories from 2026 through 2033. Limitations include unforeseen macroeconomic shifts, localized healthcare policy reforms, and trade tariff adjustments that could impact raw material pricing for critical optical components and LED drivers.
Recent Developments, Strategic Partnerships, and Product Launches
Recent industry momentum is characterized by strategic product launches featuring enhanced shadow-dilution technology and antimicrobial powder coatings. Leading manufacturers have forged critical distribution partnerships with international GPOs to streamline procurement. Recent corporate announcements emphasize investments in sustainable manufacturing practices and energy-efficient optical array designs to comply with tightening environmental regulations.